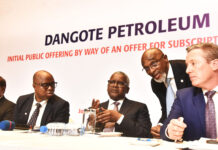
Social media influencer Martins Vincent Otse, popularly known as VeryDarkMan, has come under criticism after using a 2007 investment in Dangote Flour Mills to raise questions amid the ongoing Dangote Petroleum Refinery Initial Public Offering.
VeryDarkMan shared documents relating to an investor who reportedly subscribed for 1,200 shares in Dangote Flour Mills at ₦15 per share in 2007, amounting to an investment of ₦18,000. The documents showed dividend payments of ₦324 and ₦216 in 2009 and another ₦108 in 2012, which the activist highlighted while urging those who had subscribed to the Dangote Refinery IPO to watch his video.
The ₦15 price cited in the documents is consistent with contemporary reports of the Dangote Flour Mills public offer. The company subsequently listed five billion shares on the Nigerian Stock Exchange in February 2008 at ₦15 per share, closing its first trading day at ₦15.75. The IPO had attracted significant investor interest and was reported to have been more than six times subscribed.
However, VeryDarkMan’s post triggered a backlash on X, where several users argued that showing a handful of dividend receipts did not establish the overall return on the investment or what eventually became of the shares.
The historical record also shows that the Dangote Flour Mills story did not end with the dividend payments displayed in the video.
In 2019, Olam International moved to acquire the entire issued share capital of Dangote Flour Mills through its subsidiary, Crown Flour Mills. The transaction was subsequently approved by shareholders and regulators, leading to the company’s delisting from the Nigerian Stock Exchange in November 2019.
Under the final scheme of arrangement, qualifying Dangote Flour Mills shareholders were offered ₦24 for each share held, compared with the ₦15 IPO price in 2007. The ₦24 exit price represented a substantial premium to the company’s market price immediately before the takeover proposal, although that nominal comparison does not account for inflation, the time value of money or the investor’s complete dividend history.
If the individual whose documents VeryDarkMan displayed still held all 1,200 shares and was on the shareholder register at the relevant cut off date, the holding would nominally have been worth ₦28,800 at the ₦24 scheme price, before considering dividends, taxes, fees, inflation or any other corporate actions. The documents shared online do not independently establish whether the investor retained the shares through 2019 or received the scheme consideration.
Some social media users nevertheless accused VeryDarkMan of presenting the old investment without sufficient context.
One X user, @kelz_Realist, argued that the experience should also be viewed against the turmoil that hit the Nigerian stock market around the 2007–2008 global financial crisis.
“There’s nothing new here. The stock market crashed in 2007/08. I was affected,” the user wrote, adding that several investments made during the period suffered substantial declines.
Another user, @ajokpa, questioned expectations of unusually large returns from the initial ₦18,000 investment, asking: “How much were you expecting from an ₦18k investment in the capital market?”
@User_047 argued that investors should understand that equities inherently involve risk and that neither capital appreciation nor dividends are guaranteed.
“People expecting short term return or no risk at all should do away from any kind of Stock (IPO). Stock rise and fall everywhere in the world,” the user wrote.
Another commenter, @Oluwasheyi45, questioned whether some participants in the debate understood the distinction between shares and fixed income investments, noting that returns from equities depend partly on the performance of the underlying company.
Others went further, accusing VeryDarkMan of attempting to discourage participation in the Dangote Refinery IPO, although the activist’s presentation itself centred on questioning what became of the earlier investor’s money.
The controversy has also highlighted the danger of directly comparing Dangote Flour Mills and Dangote Petroleum Refinery, which are different companies operating in different industries, at different scales and under substantially different economic and market conditions.
Dangote Flour Mills itself went through significant ownership changes after its IPO. South Africa’s Tiger Brands acquired a controlling 63.3 per cent stake in the company in 2012. Dangote Industries later reacquired the troubled business before Olam eventually bought it in 2019.
The ongoing Dangote Refinery IPO, meanwhile, values the refinery at roughly $50 billion and seeks to raise about $1.6 billion through the sale of shares at ₦525 each. The transaction is being marketed heavily to retail investors, with a target of attracting millions of subscribers.